
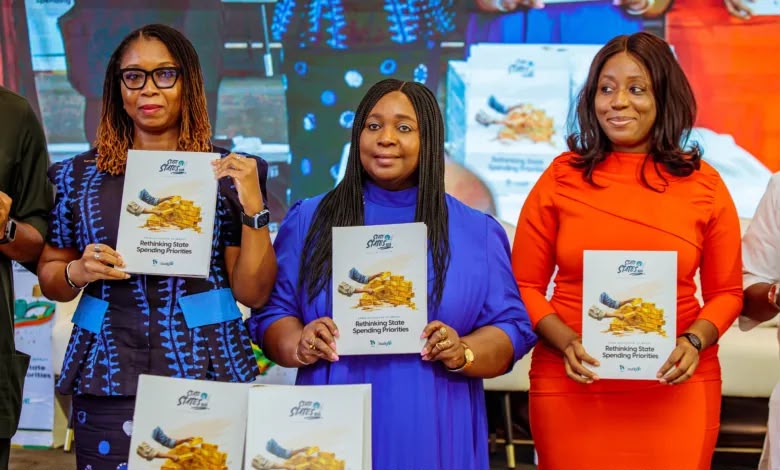
Lagos State has retained its position as Nigeria’s best-performing state in the 2026 State of States fiscal performance ranking released by BudgIT.
The 11th edition of the report, themed “From Allocation to Impact: Rethinking State Spending Priorities,” examined the 2025 fiscal performance of Nigerian states, assessing revenue mobilisation, expenditure efficiency, fiscal viability, debt sustainability and spending priorities across critical development sectors.
The report assessed 35 states, excluding Rivers State because it has yet to publish audited financial statements and budget implementation reports following the declaration of a state of emergency in 2025.
Lagos secured the top position nationally, supported by its diversified revenue base and internally generated revenue of ₦1.71 trillion.
Kebbi State also emerged as a notable performer, ranking fifth nationally after increasing total revenue by 59.54 per cent to ₦228 billion.
The report, however, emphasised that stronger revenue mobilisation does not automatically translate into better public service delivery.
The 2026 edition adopted a revised assessment methodology that places greater emphasis on the quality of public spending and its potential developmental impact.
It evaluated states across four pillars: revenue performance, fiscal viability, debt sustainability and selected critical-sector spending.
Revenue performance carried 40 per cent of the assessment, fiscal viability 30 per cent, debt sustainability 15 per cent and spending on agriculture, health, education and water, sanitation and hygiene 15 per cent.
On revenue mobilisation, the 2025 fiscal year recorded significant improvements in internally generated revenue across several states, although considerable disparities remain.
Lagos maintained its dominance, generating ₦1.71 trillion, representing a 35.67 per cent increase from ₦1.26 trillion recorded in 2024.
Enugu recorded one of the most remarkable performances, with internally generated revenue increasing by 125.91 per cent, from ₦180.5 billion to ₦407.76 billion, placing it second nationally.
Oyo and Gombe also recorded significant growth of 112.79 per cent and 111.28 per cent respectively.
Abia’s internally generated revenue increased by 64.48 per cent, while Akwa Ibom recorded 45.11 per cent growth.
Kano, the leading internally generated revenue-generating state in the North West, raised ₦102.6 billion, representing a 35.78 per cent increase.
Despite these improvements, the report highlighted the limitations of revenue growth as a standalone measure of fiscal strength.
In Enugu, non-tax receipts accounted for 90.79 per cent of the absolute increase in internally generated revenue, raising questions about the sustainability and institutional foundations of the state’s revenue expansion.
Similarly, states such as Yobe, which generated only ₦13.35 billion, and Ebonyi, with ₦21.9 billion, continue to face constraints in building sufficient domestic revenue to finance their expenditure obligations.
The report also revealed that dependence on Federation Account Allocation Committee transfers remains a defining feature of subnational public finance.
While Lagos recorded total revenue of ₦2.68 trillion, with its own-source revenue playing a significant role in recurrent receipts, several states continued to depend heavily on federation transfers.
FAAC accounted for approximately 90 per cent of Akwa Ibom’s recurrent revenue, 86.47 per cent in Anambra and 82.90 per cent in Abia.
In Kano, statutory transfers accounted for 79.28 per cent of recurrent revenue.
These figures indicate limited progress towards fiscal independence in many states and the vulnerability of their budgets to fluctuations in federation-distributed revenues.
On expenditure, the report identified a growing concern around the relationship between expanding government spending and developmental returns.
Lagos’s total expenditure increased by 33.24 per cent to ₦3.16 trillion, while Oyo’s expenditure rose by 118.71 per cent to ₦978.64 billion.
Enugu recorded an 84.80 per cent increase to ₦880.57 billion, while Abia’s expenditure grew by 44.37 per cent to ₦458.95 billion.
However, the pace of expenditure growth in some states exceeded revenue expansion, raising concerns about fiscal discipline, the sustainability of government operations and the capacity of states to meet their financial obligations.
A closer examination of operating expenses revealed further pressure on state finances.
Lagos recorded operating expenses of ₦1.29 trillion, representing a 23.89 per cent increase, while Oyo’s operating expenses rose by 88.85 per cent to ₦372.68 billion.
In Abia, operating expenses nearly doubled, increasing from ₦64.19 billion to ₦126.68 billion, driven partly by a 197.07 per cent increase in overhead expenditure to ₦70.87 billion.
Consequently, internally generated revenue covered only 53.56 per cent of the state’s operating expenses in 2025, compared with 64.28 per cent in 2024.
These trends demonstrate how rising administrative and operational costs can absorb additional revenue and limit the resources available for development priorities.
On capital expenditure, several states recorded substantial increases in spending.
Lagos increased capital expenditure by 46.69 per cent to ₦1.58 trillion, while Enugu more than doubled its capital outlays to ₦693.88 billion.
Akwa Ibom’s capital expenditure increased by approximately 85 per cent to ₦970.83 billion, while Abia and Anambra recorded ₦319.91 billion and ₦290.74 billion respectively.
Oyo’s capital expenditure also more than doubled to ₦423 billion.
However, the report cautioned that higher capital expenditure does not automatically indicate better developmental outcomes.
It stressed that what matters is the composition of expenditure, the projects prioritised, their execution and the extent to which they respond to citizens’ needs.
On debt sustainability, the report identified significant variations in the debt positions and financial obligations of state governments.
Lagos recorded a total debt stock of approximately ₦2.90 trillion at the end of 2025, while Ogun’s debt reached ₦538.92 billion, making it the fourth most indebted state in the assessment.
Enugu’s total debt increased by 18.98 per cent to ₦300.95 billion, alongside a widening fiscal deficit of ₦110.95 billion.
Conversely, Abia and Anambra recorded reductions in their total debt stocks of 8.86 per cent and 15.49 per cent respectively.
Nevertheless, foreign-currency exposure remains a significant concern, accounting for 76.06 per cent of Abia’s debt, 92.73 per cent of Anambra’s and 93.48 per cent of Ondo’s total debt.
The burden of debt servicing and accumulated liabilities further compounds fiscal pressures.
Osun’s debt service stood at ₦100.17 billion, equivalent to 28.60 per cent of its total revenue, while Ebonyi spent ₦42.51 billion on debt servicing, representing 15.99 per cent of its total revenue.
Ebonyi’s debt service obligations were almost twice its internally generated revenue of ₦21.9 billion.
The state also reported ₦43.32 billion in contractor arrears.
Abia recorded combined pension, gratuity and contractor arrears of ₦41.16 billion, while Kwara recorded ₦15.96 billion in contractor arrears and ₦23.87 billion in pension and gratuity arrears.
These outstanding obligations represent additional claims on future public resources and constrain the fiscal space available for development investments.
The 2026 edition introduced a more deliberate assessment of spending in critical development sectors, particularly agriculture, health, education and water, sanitation and hygiene.
By assigning 15 per cent of the overall fiscal performance assessment to selected critical-sector spending, BudgIT sought to strengthen the link between fiscal sustainability and human development outcomes.
Commenting on the findings, BudgIT’s Head of Research and Policy Advisory, Engr. Adejoke Akinbode, said the expansion in public revenue presents an important opportunity for Nigerian states to accelerate development.
However, she said the real measure of fiscal performance must go beyond how much money governments receive or spend.
“Our analysis shows that states are operating with significantly larger revenue envelopes, yet important questions remain about expenditure priorities, budget execution, debt management and the quality of investments in critical sectors,” Akinbode said.
“The ultimate test of fiscal responsibility is whether public resources are translated into better healthcare, improved education, productive infrastructure and other essential services that directly improve citizens’ lives.
“States must move beyond celebrating revenue growth and demonstrate measurable developmental returns on public expenditure,” she added.
BudgIT maintained that the current fiscal environment demands greater responsibility from state governments in managing public resources.
While increased FAAC allocations provide an opportunity to address infrastructure deficits and strengthen essential public services, governments must resist the temptation to expand administrative spending at the expense of productive investments.
The organisation urged states to strengthen domestic revenue institutions, adopt conservative revenue forecasts, improve budget credibility, prioritise high-impact development programmes and ensure that borrowing is directed towards investments capable of generating sustainable economic and social returns.
Ultimately, the 2026 State of States Report reinforces the need to shift the conversation on subnational fiscal performance from allocation to impact.
As governments continue to manage expanded revenue envelopes and competing development demands, citizens must be able to see tangible improvements in their living conditions.
Public resources must be managed with transparency, prudence, equity and accountability, ensuring that the benefits of fiscal reforms extend beyond government accounts to the communities and people they are intended to serve.